Does Insurance Cover Water Damage in Commercial Buildings?
Commercial property insurance may cover certain water losses, especially when the damage is sudden and accidental. A burst pipe, failed supply line, or unexpected discharge involving a building system may fit the type of event many property owners expect their policy to address. However, policy terms vary, and coverage depends on the facts of the loss.
Flood damage is different. A rainstorm that floods a 100,000-square-foot building can look exactly like a burst pipe loss once the water is inside. But the insurance treatment is different.
Flood damage is typically excluded from standard commercial property policies and often requires separate flood coverage through the NFIP or a private insurer. Water entering through a failed pipe, supply line, or internal building system is handled differently and may fall under standard commercial property coverage, depending on the policy and circumstances of the loss.
Two properties can end up with the same standing water and the same repair scope, but completely different insurance outcomes based on where the water came from.
Where water damage claims go wrong
Most water damage claims don’t fail because of the damage. They fail because of what happens in the first 48 hours.
Assuming all water damage is covered. Two losses can leave identical standing water in a hallway, but if one came from a burst pipe and the other came from a rainstorm, the insurance treatment may be completely different. We’ve restored buildings after both. The coverage question always starts with the source.
Starting demolition before testing. Some states, including Colorado, require asbestos-containing material testing before any drywall can be removed on older buildings. We’ve seen contractors skip this step, start cutting, and turn a water damage claim into an environmental remediation project that costs three times as much.
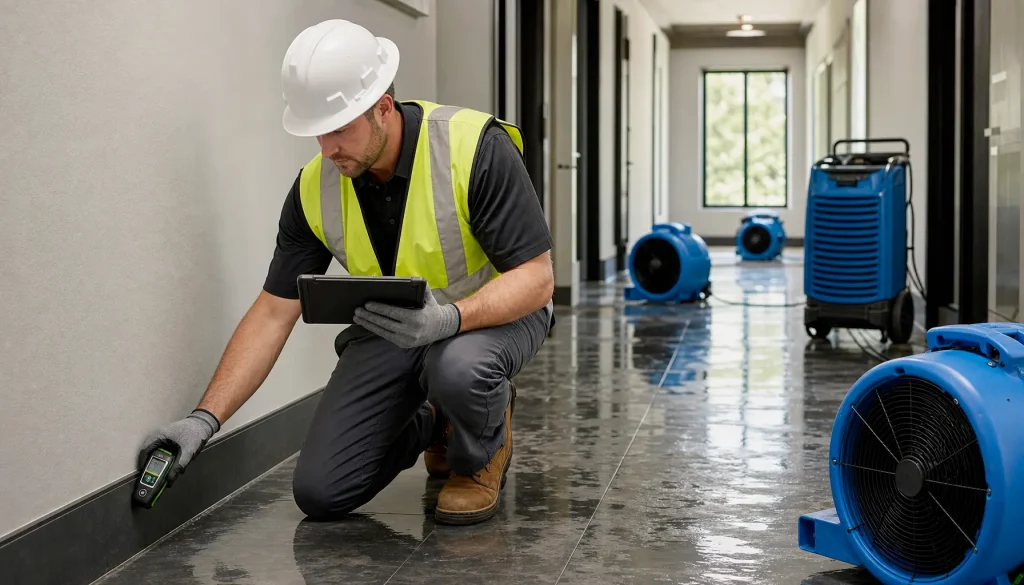
Letting moisture sit while waiting on insurance. In dry climates, surfaces can feel dry to the touch while moisture stays trapped inside wall assemblies. If it sits longer than 72 hours, biological growth starts. That’s why we map moisture levels in every affected room on day one and track drying progress daily. Guesswork doesn’t catch what’s hiding behind the walls. Verified data does.
Handing the project off three times. Many commercial losses involve one contractor for mitigation, another for environmental work, and a third for reconstruction. Each handoff creates documentation gaps, slows approvals, and increases coordination problems between adjusters, contractors, and ownership.
Treating mitigation and reconstruction as one scope. They serve different purposes and are often evaluated separately. When emergency drying and rebuild work aren’t clearly separated in the documentation, it creates confusion in how costs are reviewed and approved.
These aren’t hypothetical risks. They’re the patterns we see on real losses, and they’re the reason the first response matters more than most owners expect.
Timing and Documentation
Water damage changes quickly. Materials that look surface-wet at first can hold moisture behind baseboards, under flooring, inside insulation, or within wall cavities. When a property stays wet, the loss can become more complicated, causing environmental issues. Mold, odor, contamination, structural deterioration, and tenant disruption can increase the scope of work.
Documentation helps connect the visible damage to the source and timeline of the loss. It can also help owners communicate clearly with adjusters, tenants, board members, and internal leadership.
A strong water damage file may include photos, videos, moisture readings, equipment logs, affected-area diagrams, maintenance records, invoices, and communication history. In larger losses, that file can influence how clearly the repair scope is understood.
The immediate response should create a reliable record before materials are removed, dried, cleaned, or rebuilt.
We use Encircle documentation software to map moisture levels across every affected room, track daily drying progress, and provide the kind of data that insurance carriers require. We update our documentation at the end of each day for each loss, so adjusters don’t have to chase a contractor for the information they need to approve a claim.
Mitigation and Restoration Claims
Mitigation and restoration are related, but they serve different purposes.
Emergency mitigation is the immediate work that limits further damage. This includes stopping the water source, extracting standing water, setting drying equipment, and removing unsafe materials.
Restoration is the repair and rebuild work that follows once the property is stable.
In commercial losses, these phases are often split across multiple vendors. That creates communication gaps, fragmented documentation, and delays when adjusters review the file.
In our experience, roughly 80% of commercial water mitigation projects end up requiring a full rebuild.
Starting with a team that can manage both phases keeps the documentation consistent and reduces delays during the rebuild.
Stabilize the Property First
After water damage, property owners may feel stuck between two concerns. They want to avoid unnecessary spending, but they also need to prevent the loss from expanding. Waiting too long can increase damage, especially when water is moving through assemblies or sitting inside porous materials.
Most owners should contact their insurance professional promptly and begin documenting conditions as soon as it is safe. At the same time, they should bring in qualified help to assess moisture, control hazards, and prevent further property damage.
It means protecting the property while the facts are being gathered.
What Property Owners Should Do After Water Damage
What to do after water damage
The single most important thing you can do is shut off the water. If the source is a supply line, a valve, or a fixture, and it can be reached safely, turn it off before doing anything else. Everything that follows gets easier when the water stops running.
From there, make sure occupants are clear of affected areas and avoid disturbing materials that may involve contamination or regulated hazards. Then document the building before conditions change. Photos and videos should capture:
- The source of the water, if visible
- Affected rooms and contents
- Ceilings, walls, and flooring
- Exterior conditions
- Visible water pathways
The insurance carrier or broker should be notified promptly. It is also important to review the policy carefully, with attention to:
- Water damage coverage
- Flood and sewer backup provisions
- Mold or environmental limitations
- Business interruption coverage
- Deductibles, exclusions, and notice requirements
A Stronger Claim Starts with a Clearer First Response
Most commercial water losses become documentation, coordination, and sequencing problems long before they become reconstruction problems. The first response shapes everything that follows, from mitigation through the insurance claim and rebuild.
If you’re dealing with water damage at a commercial or multifamily property right now, contact our team. We’ll help assess the loss, stabilize the property, and build the documentation needed to support the next steps.