How Insurance Decides What to Pay for Commercial Water Damage

Spyder Construction Brand Icon
Spyder Construction
Rebuild. Restore. Renovate.
September 3, 2026
4 min read
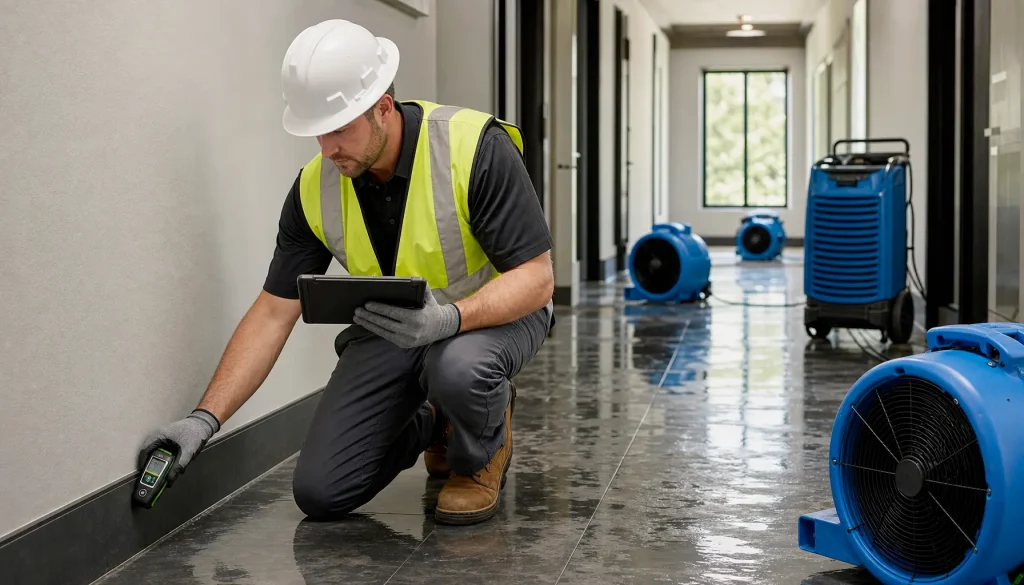
Restoration pro logging moisture in a wet commercial corridor to document a commercial water damage insurance payout

Your commercial water damage settlement came in under your contractor’s repair estimate, or you are about to file. The payout is decided more by how well the damage was documented before anyone touched a wall than by how much damage exists. How insurance decides what to pay for commercial water damage comes down to three inputs. Those are your policy coverage terms, the documentation of the scope, and the line-item scope your contractor submits.

Quick answer

An insurer builds your payout from three inputs. First, what your policy covers and how it values the loss. Second, how thoroughly the damage was documented to a professional standard. Third, the priced, line-item scope your contractor submits.

The number rarely turns on how bad the damage looks. Two buildings with identical losses can settle for very different amounts, because one claim file was documented better than the other. The one action that changes your number is documenting the full scope before demolition starts. From there, you hold the settlement against a scope you can defend line by line.

How a commercial water damage payout is calculated

A commercial water damage payout comes from three inputs:

  • Policy coverage terms. Whether the cause is covered, and whether the loss pays at replacement cost or actual cash value.
  • Documentation of the scope. The adjuster prices what was recorded to a professional standard, not what you describe later.
  • The contractor’s line-item scope. The carrier agrees to a number against a priced, itemized scope.

Miss any one input and the number drops. Documentation is the one you control most.

Input one, what your policy will actually pay

Covered cause versus excluded cause

Coverage starts with what caused the water. Sudden and accidental events, like a burst pipe or failed water heater, are usually covered. A slow leak or long-term seepage is usually excluded as wear and tear. Flood and sewer backup are typically excluded too, without a specific endorsement. How a water loss is covered depends on whether the water was sudden or gradual. Get the cause wrong and the claim can stall before valuation begins.

Replacement cost, actual cash value, and the holdback

The valuation method decides how much you collect. Replacement cost value, or RCV, pays to repair or replace the damage today. Actual cash value, or ACV, pays that minus depreciation for age and wear. Your first check is often ACV, which is why it looks low. The holdback, or recoverable depreciation, is released after repairs are finished and proven complete. The NAIC explains how insurers apply actual cash value and depreciation to a claim. Confirm which method your policy uses before you accept a figure.

Input two, the documentation that decides the number

Two identical losses settle for different amounts because of documentation quality, not damage quantity. If the moisture behind a wall was never recorded, it was never damaged as far as the payout is concerned.

That is why the first company onsite sets the documentation standard your whole claim relies on. Before demolition, document:

  • Photos and video of every affected area before drying or removal.
  • Moisture readings and daily drying logs against a professional benchmark.
  • The water source, its full path, and every room and assembly it reached.

Documenting to the ANSI/IICRC S500 standard for professional water damage restoration gives the adjuster a scope they can price confidently. Our team keeps that record continuous. After stabilizing, get interested parties to approve a rough order-of-magnitude estimate in writing, then start mitigation while an estimator builds the reconstruction estimate during drying.

Input three, the scope your contractor submits

The carrier pays against a priced scope, so its format drives your settlement. A narrative estimate gives the adjuster nothing to price. A line-item scope prices every affected material, the labor to replace it, and the drying equipment. That is why the priced scope, not the lowest bid, drives what the carrier pays.

In one occupied commercial building, a malfunctioning drinking fountain sent water across two floors. The visible source was small. The documented scope was not, and the repair reached $107,000.

Mold behind drywall or compromised framing often surfaces after the first estimate. A supplemental claim then covers the added scope, because mitigation and reconstruction are scoped and reviewed as separate line items. Confirm a supplement is available before anyone opens walls.

The payout also has limits. Outside a large loss, hotel and displacement costs are often uncovered and hit your operating budget, our operations director notes. A dollar is a dollar regardless of the budget, our CEO adds. Dragging out mitigation to save there can cost 10 to 20 times as much in displacement, in our field experience.

If the damage runs deeper than the visible source, our team documents the full scope and works it with your adjuster. Talk through your loss with our team.

What property managers should do about a lower-than-expected payout

  • If your settlement is lower than your repair estimate, request the adjuster’s line-item worksheet and compare it against your contractor’s line-item scope.
  • If secondary damage such as mold or structural rot turns up after settlement, confirm a supplemental claim is available before demolition proceeds.
  • If your first check looks low, check whether it is actual cash value, then track the recoverable depreciation released after repairs are proven complete.
  • If you disagree with the offer, your state insurance regulator explains your right to dispute a settlement.
In this article

Share this post

FAQ

Q: How does an insurance company decide what to pay for commercial water damage?
An insurer weighs three inputs. Those are your policy’s coverage and valuation terms, the documentation, and the contractor’s priced line-item scope.
Your first check is often actual cash value, so depreciation is withheld. The adjuster also prices only what the file documents.
Replacement cost pays today’s repair cost. Actual cash value subtracts depreciation for age and wear, and the first check usually uses it.
It is the amount the carrier withholds until repairs are done. Submit proof of completed work, usually final invoices, to release it.
Yes. A supplement adds scope the first estimate missed, common when mold or hidden damage appears once walls open. Confirm it before demolition.
Spyder Construction Brand Icon

Spyder Construction

Rebuild. Restore. Renovate.

Spyder Construction is a Class A General Contractor that handles emergency response, environmental services, insurance restoration, and construction services for commercial and multifamily properties. Our work is completed in occupied buildings with minimal disruption to tenants, residents, and revenue.

Our services

Commercial restoration services

Emergency Restoration Services

Emergency water, fire, and storm damage restoration across Colorado’s Front Range, with mitigation services designed to support faster, more efficient rebuilds.

Environmental Services

Mold remediation, asbestos abatement, and hazardous material decontamination – including meth, fentanyl, and lead – are handled by our licensed crews, ensuring safe removal, compliance, and a clear path to reconstruction.

Insurance Restoration

Large-loss restoration from emergency response through full rebuild. We manage water and fire damage mitigation, environmental abatement, reconstruction, and complete insurance claim documentation from start to finish.

Commercial Improvement Services

Upgrades to shared spaces and building systems that improve function and value, completed efficiently with minimal disruption to occupants.

Commercial Roofing

Commercial roofing systems built for durability, performance, and protection. We handle repairs, replacements, and upgrades with minimal disruption, keeping your building secure and weather-resistant.

Commercial Envelope and Reconstruction

Exterior restoration of roofs, siding, windows, and structural envelopes – improving durability and efficiency with minimal disruption to occupied properties.

have a project or emergency?

Tell us what’s going on and we’ll get back to you quickly with next steps. We typically reply in 1-2 business hours.

If you have an emergency? Call 24/7 (877) SPYDER-1

Tell us what’s going on and we’ll get back to you quickly with next steps. We typically reply in 1-2 business hours.

If you have an emergency? Call 24/7 (877) SPYDER-1

blog

keep reading

Practical guidance on emergency response, insurance, and restoration for commercial properties.

Same contractor for mitigation and rebuild: PM reviews a rebuild estimate in a gutted, drying multifamily corridor
Water Damage, Insurance Restoration, Environmental Services
8 min read

Why You Should Use the Same Contractor for Mitigation and Rebuild

Wondering if you should use the same contractor for mitigation and rebuild? See what a vendor handoff really costs in delays, claims, and downtime.
Restoration pro logging moisture in a wet commercial corridor to document a commercial water damage insurance payout
Water Damage
4 min read

How Insurance Decides What to Pay for Commercial Water Damage

Your commercial water damage payout came in under the repair estimate? Here is how insurers calculate it, and how to manage a claim toward a better number.
Two inspectors investigating the extent of smoke contamination in a burned unit.
Insurance Restoration, Fire Restoration
5 min read

Smoke Damage Restoration Process

Assessing the damage caused by a fire is straightforward. Figuring out the extent of smoke contamination requires some extra work.