The core difference between a capital improvement and a repair
A repair restores a building system to the condition it was already in, while a capital improvement makes it better, adapts it to a new use, or restores it after failure. That test comes from the IRS tangible property regulations, which sort the work into betterment, adaptation, and restoration. A betterment adds capacity or fixes a defect, an adaptation changes how the space is used, and a restoration rebuilds a major component.
Where the line falls on real commercial building systems
Classification depends on the unit of property. You judge the work against the system it belongs to, not the whole building. The roof, HVAC, plumbing, and electrical each count as their own system, and replacing a big enough share of one improves it.
| Building system | Usually a repair | Usually a capital improvement |
|---|---|---|
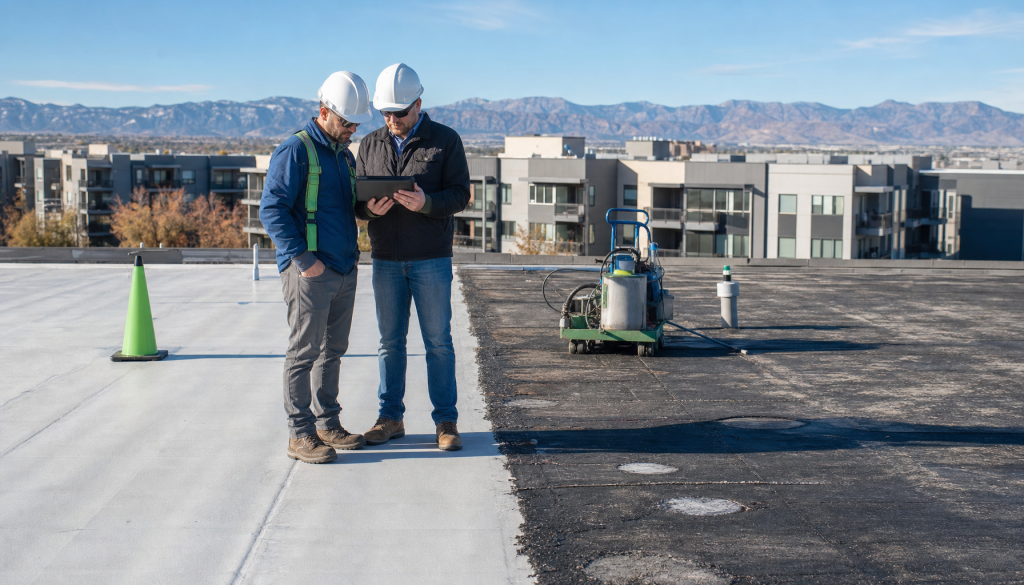
| Roof | Patching a section of membrane after a leak | A full roof system replacement, like a full EPDM-to-TPO roof system replacement on an occupied condo building, which is why the IRS treats a major-component replacement as a capital improvement |
| HVAC | Swapping one failed rooftop unit or compressor in a larger bank | Replacing the whole system or a large share of it |
| Windows and envelope | Resealing joints and replacing failed gaskets | A full window and envelope replacement that changes performance, per 26 CFR 1.263(a)-3 |
The three consequences of getting classification wrong
Your tax position
Classification decides when you get your money back. Under MACRS, commercial property is depreciated over 39 years and residential rental property over 27.5 years, while repairs are deducted in the year incurred. A project coded as capital ties up the deduction for decades.
The de minimis safe harbor in the IRS tangible property regulations lets taxpayers elect to expense items costing $2,500 or less per item, or $5,000 with an applicable financial statement. This is not tax advice, so confirm every classification with your CPA before you file.
Your insurance coverage
Improvements that raise your building’s replacement value need to be reported to your carrier, or the coverage gap shows up after a loss when the payout is capped below the real rebuild cost. After a storm, the insurance claim classification and your accounting classification can diverge, and both need documenting, as with a hail-driven roof replacement completed on an occupied community with an insurance adjuster’s agreed scope. The adjuster’s scope drives the claim, but your books still record the work for tax.
Your property’s valuation
Documented capital improvement history transfers to a buyer as asset value and speeds due diligence, while missing documentation becomes a liability the buyer prices into a lower offer.
If you are classifying 2027 budget line items and want documentation that supports your tax and insurance position, talk with our team about your capital plan.
The documentation that makes your classification defensible
A budget line item is not proof. A line that reads roof with a dollar amount says nothing about whether the work was a repair or an improvement. Three things make a classification defensible. You need the contractor’s scope of work, the completion date that sets the placed-in-service date for depreciation, and a cost breakdown separating repair work from capital work when a project contains both. Ask for all three in writing before the job closes out.
A simple if/then classification checklist
Use these rules the next time you code a budget line item.
- If an entire system was replaced, like the whole roof or HVAC, classify it as a capital improvement.
- If you replaced one worn part and the rest of the system stayed, it is likely a repair.
- If the work came from storm or water damage, the claim classification may differ from the accounting classification, so document both.
- If a project mixes repair and capital work, split the cost so each part is coded on its own.
- If capital work happened in the last three years with no documentation, treat it as a due diligence liability now.
- If you are unsure, confirm the classification with your CPA before you file.
Plan your 2027 capital work with classification in mind
Classification is easier when you plan the work with the tax and insurance outcome in mind. Spyder Construction’s capital improvement work for multifamily and commercial properties is scoped and documented so your classification holds up later, which matters most in occupied buildings, as with an occupied-building exterior capital improvement delivered without interrupting residents.
If you are planning a full-system replacement or a capital improvement in an occupied building, contact our team to talk through scope and timing.